
For an online seller, a parcel cannot be treated as only a product packed for dispatch. The shipment also carries tax information, transaction details and, in some cases, documents required during movement. Incomplete or incorrect paperwork can create problems during reconciliation, customer complaints, returns, audits and transport checks.
The gst invoicing rules ecommerce shipping businesses follow depend on the seller’s GST registration status, the type of transaction, the buyer’s location, the product category and the value of the consignment. A domestic B2C order, a sale to a GST-registered business, a cash-on-delivery order and an export shipment may each require different treatment.
This guide explains the operational rules sellers should understand before handing orders to a courier. It is written for practical shipping teams, founders and ecommerce operators. GST provisions and portal requirements can change, so treat this article as an operating guide and confirm transaction-specific decisions with a qualified tax professional.
GST invoicing rules for ecommerce shipping are the requirements that determine how a seller records a taxable sale, communicates the tax charged and supports the movement of goods. The invoice is the primary commercial document. The shipping label, airway bill or transport receipt helps identify and move the parcel, but it does not replace a compliant tax invoice when one is required.
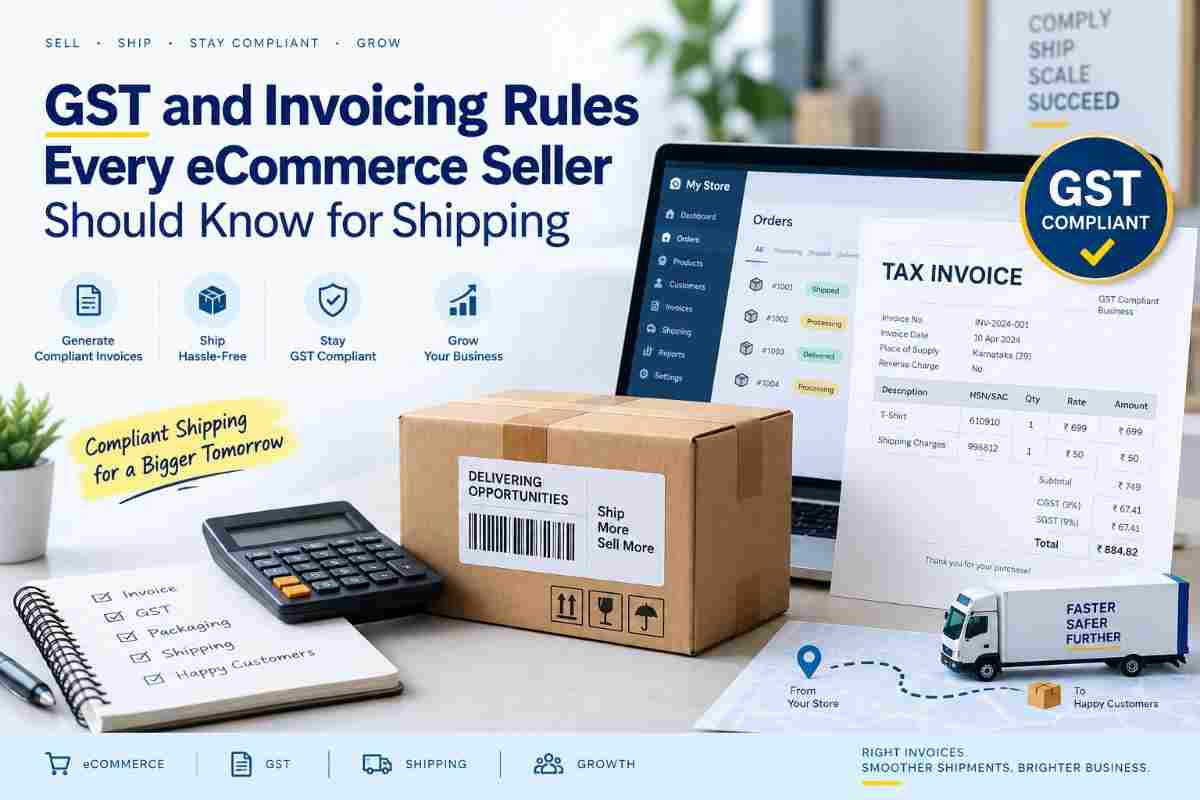
For most registered sellers, the invoice should show the seller’s legal name, address and GSTIN, a unique invoice number, invoice date, buyer details where applicable, product description, quantity, taxable value, HSN or SAC classification, applicable tax rate and tax amount. The document should also make the transaction value clear, including discounts or other adjustments that affect taxable value.
The correct tax structure normally follows the place of supply. In simple terms, an intra-state sale generally uses CGST and SGST or UTGST, while an inter-state sale generally uses IGST. This is not decided merely by the warehouse from which a courier collects the parcel. The seller must evaluate the registered location, delivery address and applicable place-of-supply rules.
These documents perform different jobs:
A seller should not assume that printing an order summary on the parcel is enough. The invoice may be provided physically, electronically or through a compliant digital process, but it must contain the required particulars and remain retrievable for records.
Shipping compliance matters because the physical movement of goods and the financial recording of the order are connected. A mismatch between the invoice, order data, package contents and courier information can make routine operations harder to defend. This becomes more important as a seller adds marketplaces, multiple warehouses, COD, interstate sales or international orders.
Tax documentation also affects customer experience. A business buyer may need a correct GST invoice to claim input tax credit, subject to the buyer meeting the applicable conditions. If the invoice has a wrong GSTIN, an incorrect state, missing tax breakup or a name that does not match the buyer’s records, the customer may ask for correction or refuse the shipment.
Good documentation helps the operations, finance and support teams work from the same transaction record. A connected billing module can be useful for maintaining invoice data alongside order and shipment records, provided the underlying tax configuration is accurate and reviewed by the business.
Compliance is therefore not only a finance responsibility. The product catalogue, checkout, warehouse, billing and shipping workflows all influence whether the final record is reliable.
A seller should first determine whether the business is GST-registered and whether the buyer has provided a valid GSTIN. A registered business customer may require a business-to-business invoice with the recipient’s legal details and GSTIN. Most ordinary consumer orders are business-to-consumer transactions, where the customer may not provide a GSTIN.
Do not enter a customer’s GSTIN without validating it and checking that the legal name and address are reasonably consistent. A wrong registration number can affect the buyer’s records and create correction work.
Invoices should use a unique, sequential and controlled numbering system for the relevant financial year or accounting structure. Separate series may be used where permitted and operationally necessary, but the logic should be documented. Cancelled invoices should not simply disappear; maintain an audit trail showing the cancellation and reason.
Each invoice should describe the product sufficiently for the transaction to be understood. Include the quantity, taxable value, discount treatment, HSN code where applicable, tax rate and tax amount. The seller should not rely on a generic description such as “online order” when the actual product category and classification are available.
HSN classification can be technical, particularly for products with different materials, uses or bundled components. Maintain a product-level tax master and have a tax professional review classifications and rates instead of changing them manually for individual shipments.
For domestic supplies, determine whether the transaction is intra-state or inter-state under the applicable place-of-supply rules. An incorrect CGST and SGST versus IGST decision can lead to tax correction and reporting issues. The delivery destination, customer registration details and the seller’s registration location should be part of the review.
E-invoicing is an electronic authentication process for invoices covered by the applicable government mandate. It is not the same as sending a PDF invoice by email. Where the requirement applies, the invoice generally needs to be reported through the prescribed system and associated with the relevant identification details before the movement or transaction workflow proceeds.
An e-way bill is a movement document used for the transport of goods when the applicable conditions are met. Its applicability can depend on consignment value, movement type, state rules, exemptions and the nature of the goods. Sellers should not assume that every parcel or every courier booking is treated identically. Check current rules before configuring an automated workflow.
Export orders involve customs and foreign-trade documentation in addition to GST treatment. The seller may export with payment of integrated tax or under an applicable Letter of Undertaking, subject to eligibility and procedure. Commercial invoices, shipping bills, product descriptions, destination details and other documents must agree with the shipment data.
International shipments should be reviewed by a tax and customs professional, particularly for restricted products, valuation, duties, refunds and marketplace arrangements. A courier label alone is not a substitute for export documentation.
A repeatable process reduces the chance that tax information changes between checkout and dispatch. The following workflow can be adapted to a small store or a high-volume operation.
For multiple selling channels, a shipping integration workflow can help centralise order and courier information. It does not replace tax review, but it can reduce duplicate entry and make exceptions easier to identify.
Strong compliance is built through controls, not through a last-minute invoice check. Sellers should document who owns each part of the process and what happens when an order does not fit the standard path.
Store the HSN classification, applicable rate, product description and tax treatment at SKU level. Review this master when products change, tax notifications are issued or a new category is introduced. Do not copy the tax code from a similar-looking product without confirming the classification.
If the catalogue includes exempt, nil-rated, zero-rated or non-GST items, configure them distinctly. A product being sold online does not automatically mean it receives the same tax treatment as every other product in the catalogue.
Payment method does not by itself decide whether GST applies to the sale. For COD orders, reconcile the invoice value, amount collected, courier deductions, remittance and refund status. A dedicated COD reconciliation process can help finance teams identify differences between orders and courier settlements.
Address changes, partial cancellations, substitutions and price changes should trigger a defined review. If the original invoice is no longer correct, use the appropriate cancellation, revised document or credit-note process rather than editing a historical record without evidence.
Connect the order ID, invoice number, SKU, package ID and tracking number wherever possible. Consistent identifiers make it easier to answer customer queries, trace a lost shipment, validate returns and support tax reconciliation.
Shipping charges may be displayed as a separate line or included in the transaction value depending on the structure of the supply and applicable tax treatment. Establish one approved policy with your tax adviser and apply it consistently across checkout, invoicing and accounting.
Keep the original invoice, return request, pickup record, inspection outcome, refund details and any credit note or replacement invoice. Reverse logistics can create tax and inventory mismatches when the physical product returns but the financial record remains open.
For international orders, use a specialist international shipping checklist covering customs descriptions, declared values, export documents and destination-country requirements. Domestic GST compliance and import duties in the destination country are separate questions.
Most errors are process failures rather than intentional non-compliance. The following problems appear frequently when stores grow faster than their internal controls.
When an error is discovered, record what happened, identify affected orders and ask the tax or accounting team which correction document is appropriate. Quietly overwriting the original record usually makes later reconciliation more difficult.
The documentation below is a practical overview, not a substitute for checking the current legal position. Specific requirements can vary based on registration, value, goods, state rules and transaction structure.
Accurate invoicing begins before the package reaches the courier. Sellers need reliable product tax data, a controlled invoice process, correct place-of-supply decisions, documented handling for COD and returns, and a clear review of e-invoice and e-way bill applicability. The tax team should confirm the legal treatment, while operations should make the approved process easy to follow.
For growing sellers, Shipmozo can support the wider execution layer through B2C Shipping, Surface Shipping, Air Shipping and International Shipping services. Used with disciplined billing and accounting controls, these capabilities can help connect shipment execution with the records your business needs to maintain.
Review your catalogue, invoice series and exception workflow before the next sales peak. For a shipping setup aligned with your order volumes and channels, Talk to an Expert
The requirement depends on the seller’s GST registration status, transaction type and applicable law. A registered seller generally needs to issue the appropriate tax document for taxable supplies, while an unregistered seller may have different obligations. Confirm the position with a tax professional.
No. A shipping label helps the courier identify and deliver the parcel. A GST invoice records the sale, supplier and buyer details, product information, taxable value and applicable tax. A label does not replace a compliant invoice where one is required.
It depends on whether the supply is treated as inter-state or intra-state under the applicable place-of-supply rules. The seller should consider the relevant registered location, delivery details and customer information instead of deciding only from the warehouse pickup location.
COD is a payment method and does not, by itself, determine the GST treatment of the sale. The seller should issue the appropriate invoice, then reconcile the COD collection, courier deductions, remittance, delivery status and any refund separately.
Not necessarily. E-way bill requirements depend on factors such as consignment value, movement type, state rules, exemptions and the nature of the goods. Sellers should check the current applicable conditions for each relevant workflow rather than applying one assumption to every parcel.
Link the return to the original order and invoice, retain the return and refund evidence, and use the appropriate cancellation, adjustment or credit-note process. The exact treatment depends on the transaction and should be confirmed with the seller’s tax adviser.
Kuldeep Karki is a Digital Marketing Manager at Shipmozo, specializing in performance marketing, SEO, and growth strategy. With over 6+ years of experience in digital marketing, he has worked extensively on scaling B2B and eCommerce brands through data-driven campaigns across Meta Ads and Google Ads.